Short answer: Buying a home in Evans, GA takes eight steps: get preapproved, sign a written agreement with your agent, tour homes, make an offer, use your due diligence window, finish your loan, close with a Georgia attorney and file for your homestead exemption. You can start with as little as 0% down on a VA loan, 3% down on some conventional loans or 3.5% down on an FHA loan, plus closing costs. Georgia has a few rules you won't find in other states, and we'll walk through each one below.
It's a Sunday night. The kids are asleep. You're scrolling listings in Evans and Columbia County, and one of them feels like home.
Then the questions pile up. How much cash do I need? Do I need a lawyer? What if the inspection finds a problem?
You're the hero of this story. You don't need to become a mortgage expert or a contract lawyer. You need a clear plan and a guide who has walked it with a lot of families. Our office is in Evans, and we walk buyers through these steps every week. Here's the plan.
The 8 Steps to Buy a Home in Evans, GA
- Get preapproved and pick a payment you're comfortable with.
- Choose your agent and sign a written buyer agreement.
- Search by commute, school zone and neighborhood.
- Make an offer with a smart earnest money deposit.
- Use your due diligence period to inspect and ask questions.
- Finish your loan: appraisal, underwriting and your Closing Disclosure.
- Close with a Georgia attorney.
- Move in and file your homestead exemption.
Want the short checklist? Our buyer's guide has it.
Step 1: Get Preapproved and Pick Your Payment
Start with a lender, not a listing.
The Consumer Financial Protection Bureau (CFPB) says prequalification and preapproval letters both tell you how much a lender is willing to lend, but they aren't guaranteed loan offers. Some lenders base a prequalification on information you simply report, and issue a preapproval only after verifying it. So ask your lender what yours is based on.
Preapproved isn't the same as comfortable. A lender shows you the ceiling. You pick the payment your family can live with. Our guide to how much house you can afford in Evans and Columbia County shows how to work backward from the monthly payment.
How Much Do You Need Down?
It depends on your loan. Here's what the major programs allow:
- VA loan: The VA says eligible buyers can get a purchase loan with no down payment, as long as the sales price isn't higher than the appraised value.
- FHA loan: HUD allows maximum financing, 3.5% down, with a credit score of 580 or higher. Scores from 500 to 579 are limited to 90% financing, or 10% down.
- Conventional loan: Fannie Mae's HomeReady program allows as little as 3% down. It's built for lower-income borrowers, so income limits apply.
- Georgia Dream: The Georgia Department of Community Affairs (DCA) offers first-time buyers a down payment loan of 5% of the price, up to $10,000. Military, educators, health care workers and other eligible groups can get 6%, up to $12,500 (amounts effective July 8, 2026). DCA's Standard program asks for a 640 minimum credit score.
Let's turn that into a real number. Columbia County's median sold price was $334,000 in October 2026, according to our October market report. Your home will be priced differently, but it's a fair yardstick:
Loan type | Down payment | On a $334,000 home |
|---|---|---|
VA | 0% | $0 |
Conventional (3% programs) | 3% | $10,020 |
FHA (580+ score) | 3.5% | $11,690 |
Down payment is only one bucket. Closing costs, prepaid taxes and insurance, and earnest money come on top. Our down payment and closing costs guide estimates closing costs at about 2% to 4% of the price. And our guide to Georgia Dream down payment help explains who qualifies.
Using a VA loan? Start with our Fort Gordon VA loan and 2026 BAH guide.
Step 2: Choose Your Agent and Sign a Written Agreement
You'll sign something before your first showing. That's normal.
Since August 17, 2024, the National Association of REALTORS® says agents who use the MLS must have a written agreement with you before touring a home together, whether in person or by live video. That agreement has to spell out what the agent will do and how much they'll be paid. NAR also says compensation is fully negotiable and not set by law.
So ask questions. What services do I get? How are you paid? A good agent will answer plainly.
Step 3: Search by Commute, Schools and Neighborhood
This is the fun part. It's also where good homework saves you the most.
Check these before you fall in love:
- The commute. Test the drive at the hour you'd really leave. Our Fort Gordon commute guide breaks it down town by town.
- The school zone. Your address picks your school, not your town name. Use our guide to find which schools serve a home before you write an offer.
- The neighborhood. Compare amenities, HOA dues and home ages. Start with our neighborhoods page, our Evans page and our Riverwood Plantation page. Our Evans subdivision guide compares prices and schools.
- The town. Still deciding between towns? Read Evans vs. Martinez vs. Grovetown and our Living in Evans, GA guide.
- The taxes. For 2026, Columbia County's rates are 4.491 mills for the county, 2.788 for fire and 14.997 for schools, or 22.276 in all, outside city limits. Our property tax guide shows what that looks like in dollars.
What Does the Market Look Like Right Now?
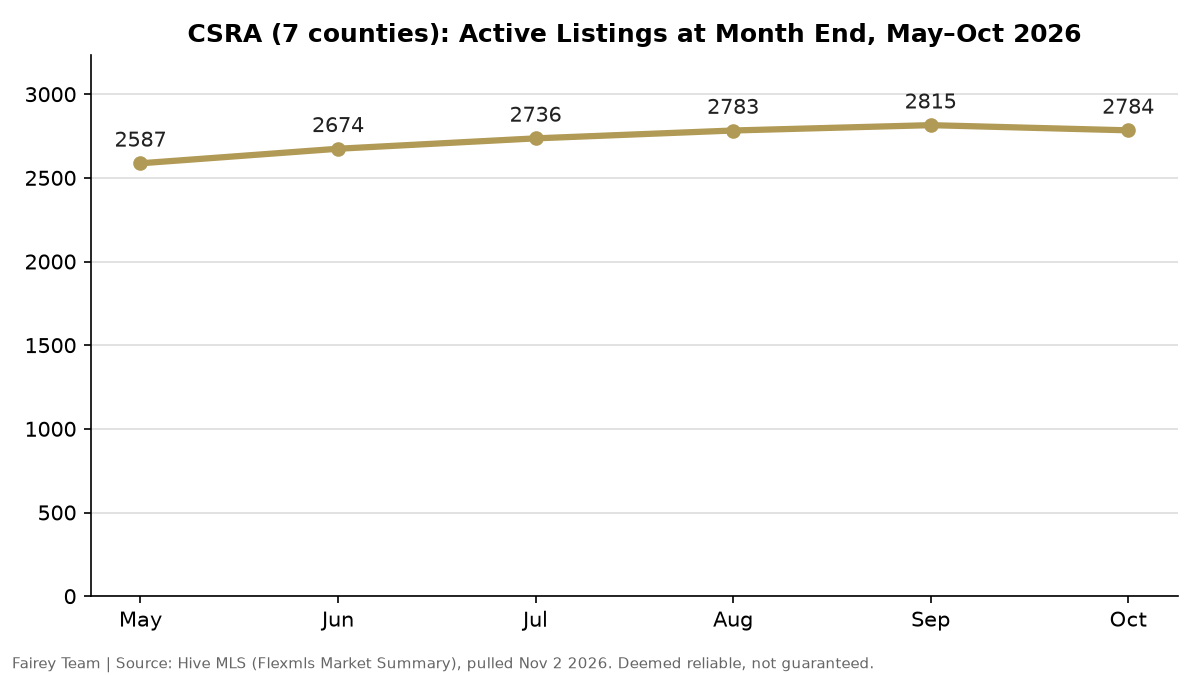
Buyers have room to breathe. In October 2026, 181 homes sold in Columbia County at a median price of $334,000, up 6.1% from last October. The median sale took 44 days. There were 840 active listings during the month, up from 805 a year earlier, and a 3.85-month supply.
That's our MLS data for the whole county. For Evans alone, the Census Bureau's 2020-2024 survey puts the median home value at $366,100, compared with $305,300 for Columbia County.
Want to feel a neighborhood before you buy in it? Spend a weekend there. This week, Jackson Dean plays the Fall Concert Series at Evans Towne Center Park on Friday, Nov. 6, from 6 p.m., and the Evans Market runs Saturday, Nov. 7, from 9 a.m. to 1 p.m. See our things to do in Evans and Columbia County this week guide. Evans on Ice returns Nov. 18, too.
Step 4: Make an Offer
When a home checks your boxes, your agent will pull comparable sales and help you decide on price, terms and timing. Three things matter most beyond the price.
Earnest money. This is a good-faith deposit, held in escrow and applied to your costs if you close. Around Evans, buyers often put down about 1% of the price or a flat few thousand dollars. Our earnest money guide explains when it's refundable.
Your due diligence length. In a Georgia contract, you negotiate how many days you get to inspect the home. Our earnest money guide says inspection periods in Evans typically run about 5 to 14 days, with many first-time buyers asking for 7 to 10.
Your financing deadline. Loan commitment windows typically run about 21 to 45 days in Evans, depending on the lender and loan type, according to our earnest money guide. Pick a date your lender can actually meet.
Step 5: Use Your Due Diligence Period
This is your safety net. Don't skip it.
Most Georgia home sales use the Georgia Association of REALTORS® Purchase and Sale Agreement, form F201. As we explain in our Georgia due diligence guide, during the due diligence period you can cancel for any reason by giving the seller written notice before it ends, and you get your earnest money back. The clock starts on the Binding Agreement Date, and it counts calendar days, weekends included.
Use those days well:
- Book the home inspection right away. Good inspectors fill up fast.
- Order a termite letter. In Georgia, the Official Wood Infestation Inspection Report is the written report used for transferring real property, and only a licensed pest control company can issue it, according to the Georgia Department of Agriculture.
- Get homeowners insurance quotes. Roof age and flood risk can change your premium.
Step 6: Finish Your Loan
After your offer is accepted, your lender gets to work. Here's the rhythm.
- Loan Estimate. The CFPB says your lender must deliver your Loan Estimate within three business days after you submit a loan application.
- Appraisal. Your lender orders an independent appraisal to confirm the home supports the loan. On a VA loan, the no-down-payment rule depends on the price not exceeding the appraised value.
- Closing Disclosure. By law, you must receive your Closing Disclosure at least three business days before closing. Compare it with your Loan Estimate and ask about anything that changed.
Our advice: until you have the keys, keep your finances boring. No new credit, no big purchases.
Step 7: Close With a Georgia Attorney
Here's the Georgia twist. Your closing is run by a lawyer, not just a title company.
In a 2014 advisory opinion, the Supreme Court of Georgia noted that, unless the parties handle it under Georgia's pro se exemption, Georgia law requires a lawyer to handle a real estate closing. That lawyer must review every document, resolve errors and title defects, and run the closing funds through a trust account. Ask your agent and lender for attorney recommendations.
Two Georgia taxes show up at closing:
- Intangible recording tax. This is on your loan. The Georgia Department of Revenue sets it at $1.50 for each $500 of the loan, with a maximum of $25,000 per note. The lender can pass it on to the borrower. On a $334,000 home with 3% down, the loan is $323,980, so the tax is about $972.
- Real estate transfer tax. This is on the sale. It's $1 for the first $1,000 and 10 cents for each additional $100. The seller is liable for it, though contracts sometimes say otherwise. On a $334,000 sale, it's $334.
Before you sign, you'll do a final walk-through to make sure the home is in the condition you agreed to. Then you sign, the loan funds and you get your keys.
Step 8: Move In and File Your Homestead Exemption
The homestead exemption lowers the taxable value of the home you live in, and it isn't automatic. The Columbia County Tax Commissioner says you must apply by April 1 to get the tax benefit for that year. You must own the home and live in it as your permanent residence on January 1. So if you close this fall, you'll own it on January 1 and can file in the new year. The office is at 630 Ronald Reagan Drive, Building C, in Evans.
Our homestead exemption walkthrough lists exactly what to bring. And our first 30 days checklist covers your driver's license, car tag, trash service and more.
Selling a Home First?
Lots of Evans buyers have a house to sell, too. The smart move is to know what your home is worth before you shop. Get your home value and we'll talk through whether to sell first, buy first or line up both.
What's at Stake
Most buying regrets aren't about the house. They're about skipped steps. A buyer runs out of due diligence days. Another learns the home is zoned to a school they didn't expect. Another budgets for the down payment and forgets closing costs. Every one is avoidable with a plan.
Your Simple Plan
- Talk with us. Tell us your budget, your commute and what a good Saturday looks like.
- Get preapproved. We'll connect you with local lenders who do your type of loan.
- Tour with a plan. We'll check the school zone, the commute and the taxes for every home you like.
- Close with confidence. We'll walk with you from offer to keys.
Picture it. A cool Saturday morning in Evans. Your keys are in your pocket, and you already know your commute, your school zone and your tax bill because you checked before you bought.
Why Families Trust the Fairey Team
We live here. We're raising our three kids here. And we know what it's like to move. Our Team Lead, Ehrin, serves in the Air Force Reserve, so we understand PCS orders and buying from far away. Military families can start with our military relocation page. You're the hero of this move. Our job is to be a good guide.
Frequently Asked Questions
How do I buy a house in Evans, GA?
Follow eight steps: get preapproved, sign a written agreement with your agent, search homes, make an offer, use your due diligence period, finish your loan, close with a Georgia attorney and file your homestead exemption. A local agent can check the school zone, commute and taxes for each home along the way.
How much do I need to buy a house in Georgia?
It depends on your loan. A VA loan can require no down payment, FHA requires 3.5% down with a 580 credit score, and Fannie Mae's HomeReady allows 3% down for eligible borrowers. You'll also need closing costs, prepaid taxes and insurance, and earnest money. Georgia Dream may help eligible first-time buyers with up to $10,000, or up to $12,500 for certain professions.
Do you need a lawyer to buy a house in Georgia?
In nearly every case, yes. The Supreme Court of Georgia has noted that, unless the parties handle it under Georgia's pro se exemption, Georgia law requires a lawyer to handle a real estate closing. Your closing attorney reviews the documents, resolves title problems and handles the closing funds.
How long does it take to buy a house in Georgia?
It depends on your contract and your lender. You'll negotiate a due diligence period, typically about 5 to 14 days around Evans, and a financing deadline that typically runs about 21 to 45 days. Your closing date is set in your contract, so pick dates your lender and inspector can meet.
What is the due diligence period in Georgia?
It's a set number of days in your contract when you can inspect the home and cancel for any reason, with written notice before the period ends, and keep your earnest money. After it ends, backing out can cost you your deposit.
What credit score do I need to buy a house in Georgia?
It depends on the loan. For FHA, a score of 580 or higher qualifies for 3.5% down, and 500 to 579 requires 10% down. Georgia Dream's Standard program requires a 640 minimum score. Individual lenders may set higher minimums, so ask yours.
What are closing costs in Georgia?
They include lender fees, the appraisal, title work, your closing attorney and prepaid items, plus Georgia's intangible recording tax on your loan. The transfer tax is the seller's by law, though a contract can assign it. Our guide estimates total closing costs at about 2% to 4% of the price, and your Loan Estimate will show your real number.
Do I need a buyer's agent, and who pays them?
You can buy without one. If your agent uses the MLS, you'll sign a written agreement before touring a home together. It states the services you get and how much your agent is paid, and the compensation is negotiable. Ask who pays before you sign.
When do I file for the homestead exemption in Columbia County?
File with the Columbia County Tax Commissioner by April 1 to get the benefit for that year. You must own the home and live in it as your permanent residence on January 1. It's not automatic, so put it on your calendar.
Let's Find Your Home in Evans
Ready to start? Let's take a drive. We'll talk about your budget, map your commute and show you the neighborhoods that fit your life.
- Call: (706) 480-5203
- Email: [email protected]
- Visit: 2580 Evans Trade Center, Evans, GA 30809
- Next step: Explore neighborhoods · Evans homes · Military relocation help · Get your home value
New to the area? Start with moving to Evans and Columbia County and see whether Evans and Columbia County is a good place to live. Got more questions? Our real estate FAQ has answers.
Photo: "Hand holds house keys near door lock, symbolizing new beginnings and homeownership journey in a modern setting" by Shixart1985, CC BY 2.0, via Wikimedia Commons. Cropped to 16:9 and resized.